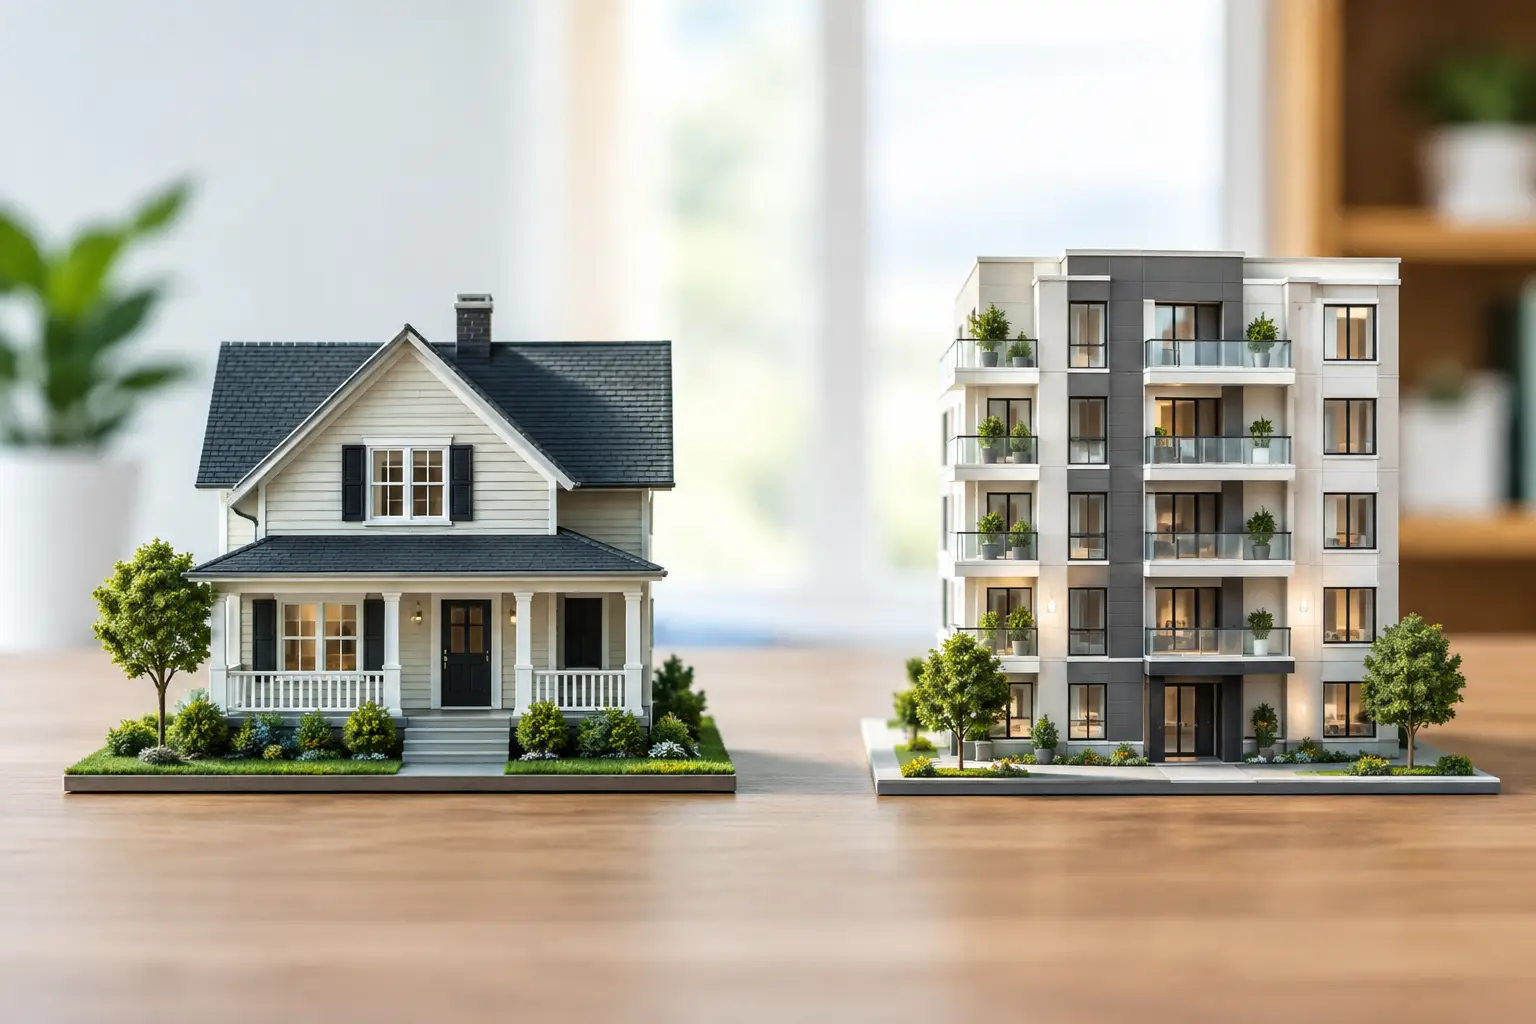
A house with a backyard can feel like the obvious next step. But a well-located apartment may put you closer to work, transport, schools, restaurants and the lifestyle you actually use each week. In house versus apartment buying, the right choice is rarely about which property type is better overall. It is about which works best for your budget, household and next five to 10 years.
The purchase price is the starting point. costs, lending conditions, maintenance, flexibility and resale demand can change the real value of a property considerably. Start by looking beyond the floorplan and asking what ownership will require from you over time.
House versus apartment buying: start with your priorities
A house generally offers more land, privacy and control. You can renovate, extend, landscape and make changes without needing approval from an owners corporation, subject to council requirements. For families planning to stay put, the extra bedroom, outdoor space and storage can be worth paying for.
An apartment can offer a more accessible entry point into a sought-after suburb. It may also reduce the time and cost involved in maintaining a property. For first-home buyers, downsizers, busy professionals and investors, that convenience can be a meaningful advantage.
The question is not simply whether you want a garden or a balcony. Consider how you live now and what is likely to change. A couple expecting to work from home long term may value a separate study more than proximity to the CBD. A family with young children may place greater value on a secure courtyard, local parks and school catchments. Someone who travels often may prefer a lock-up-and-leave apartment with secure parking.
Compare the full cost of ownership
A lower purchase price does not always mean a lower-cost property. Before making an offer, estimate the upfront and recurring expenses for each option.
For a house, the major costs can include council rates, building insurance, repairs, gardening, pest control and eventual big-ticket work such as roofing, painting, fencing or replacing a hot-water system. Land size can add value, but it also brings responsibility.
Apartment owners usually pay strata levies, which fund shared areas and services such as insurance, lifts, cleaning, security, pools and gyms. Levies vary sharply between buildings. A simple walk-up block may have modest fees, while a newer high-rise with lifts, concierge services and extensive amenities can be expensive to run.
Ask to see the strata records before committing. The meeting minutes, budget, sinking fund balance and planned works can reveal more than the advertised quarterly levy. A low levy is not automatically good news if the building has insufficient funds for expected repairs. Special levies for major façade, waterproofing, lift or fire-safety work can be substantial.
State-based costs also matter. Stamp duty, first-home buyer concessions, land tax rules and building regulations differ across Australia. Speak with a conveyancer or solicitor early, particularly if you are buying your first property or considering an investment.
Finance can differ by property type
Lenders assess apartments differently depending on the building and location. Some may apply tighter lending criteria to very small apartments, certain high-density developments, serviced apartments or properties with unusual ownership structures. This does not mean finance is impossible, but it can affect your deposit requirement, valuation and lender choice.
For both houses and apartments, get pre-approval before you become emotionally invested. It gives you a realistic price range and allows you to move quickly when the right property appears.
Space, location and daily convenience
Houses typically win on internal space, land and separation from neighbours. You are more likely to have room for pets, hobbies, storage, a growing family or future improvements. In established suburbs, a house may also offer stronger access to local schools and community facilities.
Apartments often win on location. Being closer to a train station, employment hub, beach, university or major shopping precinct can save time every day. A smaller home in the right location may support a better routine than a larger home that adds an hour of commuting.
Be realistic about the compromises. A house on a busy road may not deliver the quiet or privacy you imagined. An apartment with excellent transport access may still be a poor fit if you need room for sporting equipment, a large dog or regular overnight guests. Visit at different times of day, check traffic and noise, and walk the route to transport, shops and schools rather than relying on a map.
Understand control and maintenance
Owning a freestanding house gives you broad control over the property, but every maintenance decision is yours to make and fund. That independence suits buyers who want to personalise a home or add value through renovation. It can be less appealing if weekends spent organising trades are not part of your plan.
With an apartment, the owners corporation manages common property, but shared decision-making comes with rules. You may need approval for flooring changes, renovations, pets, installing air conditioning or renting the property. Read the by-laws carefully. They shape everyday life, from parking and balcony use to short-term letting restrictions.
Building quality deserves close attention. For apartments, arrange an inspection and review the strata report for defects, water ingress, cladding issues and upcoming capital works. For houses, a building and pest inspection is essential, especially where there are signs of drainage problems, cracking, termite activity or ageing structures.
Think about future value without guessing
Land scarcity is reason houses have historically appealed to many long-term buyers. In suburbs with limited detached housing and strong family demand, the land component can support price growth. But a house is not automatically a better investment. Location, condition, street appeal, transport, school zones and local supply remain decisive.
Apartments can perform strongly where buyers value convenience and where supply is controlled. Character blocks in established inner-city or beachside locations can attract consistent demand. By contrast, an area with a large pipeline of near-identical new apartments may face more competition when it is time to sell or lease.
Look at recent comparable sales rather than broad headlines. Compare properties with similar bedrooms, parking, condition, building age and location. For apartments, consider the number of dwellings in the complex and whether competing buildings offer similar features. For houses, compare land size and renovation quality as well as the home itself.
Make a decision you can hold comfortably
A useful test is to picture the property after the excitement of buying has faded. Can you comfortably meet repayments if rates, strata levies or maintenance costs rise? Does the layout still work if your household changes? Would you be content staying there for several years if the market is slower than expected?
Before you bid or negotiate, answer four practical questions:
- Do I value space and autonomy more than a central location and lower maintenance?
- Have I budgeted for every recurring cost, not just loan repayments?
- Have I reviewed the building, strata or planning risks properly?
- Will this property suit my likely needs for at least the next five years?
There is no universal winner in house versus apartment buying. A house may be the better choice for buyers seeking space, land and long-term flexibility. An apartment may be the smarter move for those prioritising location, convenience and a manageable entry price.
Use recent sales, suburb information and listing history to test your assumptions before you act. On Leading Agents, comparing similar homes across your preferred suburbs can help you see where your budget delivers the lifestyle and property fundamentals you want. The strongest purchase is the that fits your life now, leaves room for change and remains financially comfortable after settlement.